


Step-by-step process to getting the keys to your new home.
-
- monday: 8:00AM – 5:00PM
- tuesday: 8:00AM – 5:00PM
- wednesday: 8:00AM – 5:00PM
- thursday: 8:00AM – 5:00PM
- friday: 8:00AM – 5:00PM
-
- Conventional Loan
- FHA Loan
- First-Time Homebuyers
- Home Equity
- Purchase
- Refinance
-
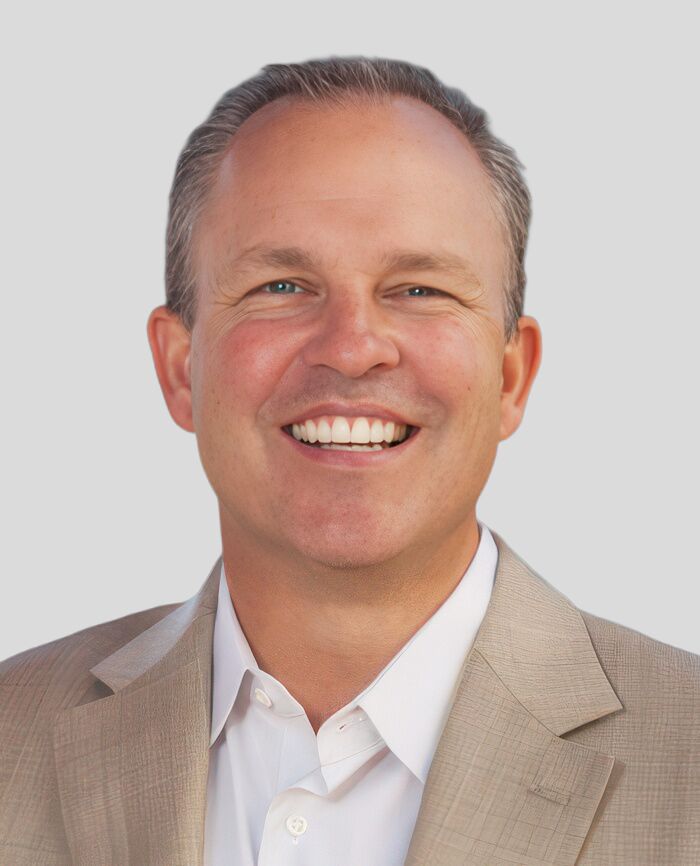
Your Local CrossCountry Mortgage Loan Officer
Nick Brady
I’ll be with you every step of the way
Hello! I’m Nick, and I’m proud to help homeowners 62 and older make the most of the home equity they’ve built. As a Loan Originator at the Cleveland, OH branch of America’s #1 Retail Mortgage Lender, I specialize in reverse mortgages — also known as Home Equity Conversion Mortgages (HECMs) — to help you access funds while staying in the home you love.
Whether you’re looking to supplement retirement income, cover medical expenses, make home upgrades or move into a new home, I’ll walk you through your options with clarity and care. I understand that this is a major financial decision, and I’m here to help you make it with confidence.
I’ll take the time to explain how reverse mortgages work, answer your questions and help you explore whether it’s the right solution for your current situation and future goals.
With a trusted advisor by your side, you can feel secure unlocking the value of your home — to live more comfortably today and plan more confidently for tomorrow.


Nick’s Reviews
Guides and resources


My social posts
How much will my mortgage payment be?
This calculator is being provided for educational purposes only. The results are estimates based on information you provided and may not reflect CrossCountry Mortgage, LLC product terms. The information cannot be used by CrossCountry Mortgage, LLC to determine a customer’s eligibility for a specific product or service.
Inspiration for your home loan journey


Frequently asked questions
-
Refinancing costs typically range from 2% to 6% of the loan amount and include fees such as appraisal, title insurance, and closing costs. Factors like your loan type, location, and credit score can significantly impact these expenses. Our team can help to provide strategies that can help minimize costs.
-
To determine how much home you can afford, you’ll want to assess your financial situation. This includes your income, expenses, and debt-to-income ratio, to ensure your mortgage fits comfortably within your budget. A general guideline is to spend no more than 28% of your gross monthly income on housing costs and 36% on total debt.
-
A good credit score typically starts at 620 for conventional loans, while FHA and VA loans may accept scores as low as 500, though higher scores offer better terms. A strong credit score can help you secure lower interest rates, saving you significant money over the life of a home loan.
-
A Home Equity Line of Credit (HELOC) is a revolving line of credit that allows homeowners to borrow against the equity in their home. HELOCs function like a credit card, giving access to funds up to a set limit, which can be used for expenses like renovations or debt consolidation. You only pay interest on the amount you borrow, and the repayment terms typically include a draw period followed by a repayment period.
-
To calculate your mortgage payments, start with your loan amount, interest rate, and loan term. Your payment will depend on the interest charged over time and the repayment schedule. You can use a monthly mortgage payment calculator or connect with us to learn more.